Engine Coolant Level: How to Check, Top Up and Replace It
Table of Contents:
|
Radiator water is the engine coolant that circulates between the engine and the radiator to carry heat away and protect the system from corrosion and boiling. To check the engine coolant level safely, park on level ground, wait until the engine is completely cold, then look at the fluid in the reservoir (expansion tank) from the outside; the normal level is usually between the MIN and MAX marks. If it is low, top up with coolant that matches the owner’s manual up to MAX, and never open the radiator or reservoir cap while the engine is hot. Repeated loss, however, may point to a leak that needs checking by a qualified technician.
What Is Radiator Water and Why Is Plain Water Not a Substitute?
What many drivers in Saudi Arabia call radiator water is actually coolant, also known as antifreeze, which is mixed with water in a ratio set by the manufacturer. It contains additives that protect the system’s metal parts from corrosion, raises the boiling point of the fluid inside the pressurised system and lowers its freezing point. To understand the role of the radiator itself and its parts, see the guide to radiator function, types and care.
Plain water alone does not provide this protection, and adding it dilutes the existing coolant, weakening its protection against corrosion and boiling; depending on its mineral content it may also leave deposits. It should only be used as a temporary emergency measure to reach a safe place if the owner’s manual allows it, after which the system should be refilled with the correct coolant at the specified concentration as soon as possible. For colours and types, see the risks of using the wrong radiator fluid, bearing in mind that colour alone does not define the specification.
Where Is the Coolant Reservoir and What Do the MIN and MAX Marks Mean?
In most modern cars you do not need to open the radiator to read the level; there is a semi-transparent plastic tank in the engine bay called the reservoir or expansion tank, marked MIN for the lower limit and MAX for the upper limit, sometimes shown in another form such as LOW and FULL. The level rises as the engine heats up and falls as it cools, which is why the reading is taken with a cold engine.
Locate the reservoir in the owner’s manual, and do not confuse it with the washer fluid tank or the brake fluid reservoir. In some designs the reservoir cap is the pressure cap for the system, so treat it with the same caution as the radiator cap.
How Do You Check the Engine Coolant Level With a Cold Engine?
- Park on level ground, switch the engine off and apply the parking brake.
- Wait until the engine is completely cold; checking before the first start of the day or after a long stop is best, and do not rely on the temperature gauge dropping alone.
- Look at the fluid level through the side of the reservoir without opening the cap; the normal level is between MIN and MAX.
- Note the colour and cleanliness of the coolant, and any deposits or oily film on its surface.
- Inspect the ground under the front of the car and the visible hoses for signs of leaks.
Important warning: never open the radiator cap or a pressurised reservoir cap while the engine is hot or warm, because the coolant is under pressure and steam and hot fluid can spray out and cause burns. In the Saudi summer the engine bay may stay hot for longer after switching off, so allow enough time before touching any part. Make the check a regular habit and do it before trips, following the owner’s manual recommendations.
How Do You Top Up Coolant Correctly?
- Choose the type specified in the owner’s manual by its written specification, not by colour or appearance.
- Check the type of product: ready-to-use premixed coolant is added as it is, while concentrate must be diluted before adding, using the type of water and the ratio stated on the product label or in the manual.
- Do not mix two different types unless the manual allows it, and if you do not know which type is in the car, ask a technician.
- Once the engine is fully cold, open the reservoir cap slowly using a cloth, and add coolant to the reservoir rather than the radiator unless the manual says otherwise, up to the MAX mark without exceeding it, then close the cap firmly.
- Wear gloves, wipe up any spills immediately, and keep containers away from children and animals, because coolant can be poisonous if swallowed.
If the reservoir has run dry or the level has dropped a lot, air may have entered the system, and removing it is a job for a qualified technician.
What Signs May Indicate Low Coolant or a Leak?
- A distinctive sweet smell around the car or inside the cabin.
- Coloured puddles under the front of the car, or dried residue and crust around hoses and joints.
- White steam rising from the engine bay.
- A rising temperature gauge on the dashboard, or a temperature warning light or low coolant message.
- Cold air from the heater even though it is set to hot after the engine has warmed up.
These signs are only indications, and more than one problem can share the same sign. A leak may come from a hose, the radiator, the cap or the water pump; for pump symptoms specifically, read about the functions of the water pump and signs of failure. If the temperature does rise, read the main causes of engine overheating and what to do, and do not keep driving with a red temperature warning.
What Does Each Situation Mean and What Should You Do?
| Situation | What it may indicate | What to do |
| Level below MIN with a cold engine | A leak or gradual loss of coolant | Top up with matching coolant to MAX and watch the level |
| Needing to top up again and again | An external or internal leak, or a cap that does not hold pressure | Have the system checked by a technician rather than just refilling |
| Coloured puddles and a sweet smell under the car | A leak from a hose, the radiator or the pump | Have a technician find the source before long journeys |
| White steam with a rising temperature gauge | Overheating or a leak of hot coolant | Stop safely, switch the engine off and do not open any cap |
| Discoloured coolant, deposits or oil in it | Aged or contaminated coolant | Ask for an inspection and check the change interval in the maintenance schedule |
| Level above MAX with a cold engine | Previous overfilling | Add nothing and ask the technician to correct the level |
Why Does Radiator Water Keep Dropping?
Coolant works in a closed system, so it should not drop noticeably and repeatedly. If you need to top up again and again, this may point to a small external leak that evaporates before leaving a puddle, a cap that does not hold pressure, or an internal leak in the engine, which may come with signs such as thick white smoke from the exhaust or a change in the appearance of the engine oil.
Do not rely on repeated refilling; ask the technician to check the system with suitable tools such as a pressure test, and tell them how often you added coolant and when. In the opposite case, where the temperature rises while the level stays stable, the problem may lie in circulation or cooling itself; see the guide to overheating without coolant loss and safe action.
When Is It Time to Replace the Coolant Completely?
The protective additives in coolant are gradually used up, which is why the manufacturer sets the change interval in the maintenance schedule of the owner’s manual, and it may differ by coolant type and operating conditions. Follow the schedule, and ask for an inspection earlier if the coolant changes colour or shows deposits or traces of oil.
A complete change involves draining the system, possibly flushing it, then refilling with the matching coolant and removing trapped air, which is work best left to a workshop. In Saudi heat, with traffic and long air conditioning use, the cooling system works under a higher load, so check the level and hoses before summer and trips. Do not pour old coolant into drains or onto the ground.
Frequently Asked Questions About Radiator Water
Can I put plain water in the radiator?
Only in an emergency and if the owner’s manual allows it, because water dilutes the coolant and weakens its protection; refill with the correct coolant as soon as possible.
What is the normal radiator water level?
It is usually between the MIN and MAX marks on the reservoir when checked with a cold engine. A reading with a hot engine is higher because the coolant expands, so do not rely on it.
Why does water come out of the radiator when the car overheats?
This can happen when the coolant boils or its pressure rises, pushing it out through the cap, the overflow outlet or a leak point. Stop safely, switch the engine off and keep away from the steam, do not open any cap until it has cooled, then have the cause checked.
Can I mix coolant of a different colour or type?
This is not recommended unless the owner’s manual or the product label allows it. If you do not know which type is in your car, ask the technician before topping up; the solution may be a complete coolant change.
What is the best type of car coolant?
The best type is the one that matches the specification in your owner’s manual, not the most popular one or one of a particular colour. Look for the specification on the container label, and choose premixed coolant if you are unsure about dilution.
Conclusion
Check radiator water with a cold engine from outside the reservoir, keep the level between MIN and MAX with the coolant specified in the owner’s manual, and never open any cap while the engine is hot. Plain water is only an emergency measure; repeated loss or signs of a leak call for a technician’s inspection, and a complete change is due according to the maintenance schedule.
Overheating Without Coolant Loss: Causes and Safe Action
Table of Contents:
|
Overheating without coolant loss is possible: coolant visible in the reservoir does not prove that it circulates through the engine or releases heat effectively. The fault may involve coolant flow, airflow or cooling controls, and the temperature reading itself may also need checking. If an overheating warning appears, stop somewhere safe, switch off the engine and request assistance. Do not keep driving because the reservoir looks full.
Overheating Without Coolant Loss: What Does a Stable Level Mean?
The everyday expression water level refers here to engine coolant, not a recommendation to use plain water. This article focuses on a level that appears normal despite an overheating warning. For the wider picture, see the guide to engine overheating causes and what to do.
The reservoir’s role and the method for reading its level depend on the cooling-system design: it may be a pressurized part of the system or a recovery tank. Coolant also expands when hot, so comparing a hot reading with a cold one cannot establish system health. A visual reading within the marks on a cold engine, following the manual, tells you only about the level. It does not prove that passages are free of air or restrictions, or rule out a fault or a leak whose effects are not yet apparent.
How Can the Engine Overheat When Coolant Is Present?
The cooling system must move heat away from the engine and then transfer it to the air through the radiator. A failure at either stage can raise the temperature without an obvious drop in level. These are possibilities for inspection, not a shopping list of replacement parts:
- Fan or fan control: insufficient air may pass through the radiator while stationary. Seeing a fan turn once does not prove that its speed or all operating modes are correct.
- Thermostat: if it does not regulate coolant passage correctly, heat transfer to the radiator may be impaired despite an apparently adequate amount in the reservoir.
- Trapped air: air can interfere with coolant movement and heat transfer, particularly if the problem started after cooling-system work. The timing is a clue for the technician, not proof of a diagnosis.
- Insufficient pumping: the water pump may not provide the required flow. This does not necessarily produce a visible leak or an obvious noise that the driver can identify.
- Restricted heat exchange: internal restrictions in radiator passages or an external obstruction to airflow can reduce cooling. Reservoir level cannot distinguish between them.
- System pressure: a fault in the cap or components that retain pressure can affect the coolant’s resistance to boiling. Never test a cap by removing it while hot or guess at a different pressure rating.
For an explanation of circulation specifically, read about the water pump’s role in circulating coolant. Mentioning the pump does not make it the most likely cause in your car, and replacing it without checking the rest of the system may not solve the problem.
What Can Traffic and Highway Patterns Tell You?
Record only the conditions you already observed during previous use. Do not drive again or leave the engine running to reproduce overheating. The pattern can help a workshop organize its checks, but it is not a conclusive diagnosis:
| Previous observation | What might the technician check? | What does it not prove? |
| Temperature rises at a stop and eases when moving | Airflow, fan performance and fan control | It does not prove that only the fan is faulty |
| The warning appears on the highway or uphill | Coolant flow and heat exchange under load | It does not identify the pump or radiator specifically |
| It began after a coolant change or repair | Correct filling, trapped air and connections | It does not confirm trapped air without checks |
| It coincides with air conditioning use | Cooling performance as load and airflow change | It does not prove low AC refrigerant |
If the connection with AC use is your main observation, there is a separate explanation of engine overheating when the air conditioning is on. The key point here is that a normal coolant level cannot rule out a cooling fault, whatever the conditions when the warning appears.
Could the Temperature Reading Be Wrong?
A temperature sensor, its wiring or the display system may affect the reading. However, do not assume the warning is false because the reservoir is full or you cannot see steam. Some cooling faults show no obvious external sign at first. Treat the warning seriously until a qualified technician verifies the actual temperature and readings.
The technician compares diagnostic data and appropriate measurements with the vehicle’s specifications and operating conditions. A fault code alone cannot condemn a part, and the absence of a code does not prove that cooling is normal. There is also no single operating temperature for every car. Use the owner’s manual and vehicle-specific service information to interpret the gauge and warning message.
What Should You Do Safely When the Warning Appears?
- Move to the nearest safe stopping place away from traffic and use hazard lights as needed. Stop and switch off the engine. Do not try to drive to a workshop with an overheating warning.
- Stay clear of steam and spraying fluid. Never open a hot radiator or coolant reservoir cap, and do not assume that pressure has disappeared just because the gauge has fallen.
- Do not work near fans or put hands or tools in their operating area: a fan may start automatically even after the engine is switched off. Do not test it by hand or touch hot hoses.
- Do not pour cold water onto a hot engine or add fluid to a hot system. Request roadside assistance and arrange transport for inspection rather than repeatedly restarting the engine to see what happens.
Once the engine has cooled completely, you may record the level visible from outside the reservoir if this is possible and safe according to the manual, without removing caps or parts. A normal level or a warning that disappears after shutdown does not establish that the fault has gone or that continuing the journey is safe.
What Information and Checks Should You Discuss With the Workshop?
Tell the technician when the warning appeared: while stopped, climbing or travelling. Mention any preceding service work or fluid addition. Describe the message and any smell or steam you noticed from a safe position. Photograph the dashboard only after stopping, and do not reproduce the fault for documentation.
- Ask for the coolant level, specification and system condition to be checked, rather than accepting the reservoir is full as the entire assessment.
- Discuss fan operation and control, thermostat and pump function, and radiator flow as indicated by the diagnostic findings.
- Leave pressure and cap testing and air-removal procedures to the technician, using tools and methods appropriate to the system design.
- Ask what evidence identifies the fault and which check verified the repair before the car is handed back.
If initial checks do not identify the cause, broader diagnosis may be necessary. Do not jump to a head-gasket diagnosis, or rule it or another internal fault out solely because the reservoir level is stable. Testing should determine the next step.
Why Is Adding Water Not a Universal Fix?
If the level is within the correct limits, adding fluid will not repair a fan or restore impaired flow, and may exceed the permitted fill level. Use coolant meeting the vehicle’s specification and the concentration stated in the manual. Plain water is not a universal substitute, and color alone does not establish compatibility. Read about coolant differences and choosing a suitable fluid for more context.
Do not mix unknown products or experiment with additives to treat overheating. Flushing and air removal are not identical procedures on every vehicle; leave them to a professional when technically justified. Maintaining the correct level matters, but it is only one part of system health, not a replacement for checking performance.
Frequently Asked Questions About Overheating With a Stable Level
Does a full reservoir mean the radiator is full?
Not necessarily; it depends on the system design and condition. The visible level alone does not prove correct filling or circulation, and never justifies opening a hot cap.
Does the absence of a leak rule out pump failure?
No. Leakage is not the only possible sign of a pump fault. Its ability to circulate coolant needs appropriate assessment, not just a look underneath the car.
Can I drive if the gauge drops after stopping?
A lower reading does not prove the fault has gone. After an overheating warning, do not resume driving to test the car; request assistance and inspection before using it again.
Should I remove the thermostat to solve the problem?
Do not remove the thermostat as an experiment: it is part of cooling regulation. A technician should assess it and fit the correct replacement if necessary.
Does overheating without coolant loss mean a faulty sensor?
No. The overheating can be real despite a stable level. Do not ignore the warning or disconnect the sensor; have the reading and system performance checked together.
Conclusion: Check Cooling Performance, Not Just the Level
A stable coolant level neither rules out overheating nor identifies its cause. Stop safely at a warning, switch off the engine, avoid hot caps and fans, and give your observations to a qualified technician. A sound repair starts with evidence of the fault, not extra water or random parts replacement.
Driving License Renewal on Absher: Requirements and Steps
Table of Contents:
|
Driving license renewal in Saudi Arabia is done electronically through the Absher platform under traffic services, without visiting traffic offices, provided you complete the regulatory requirements such as paying the fees and completing a medical examination. This electronic service covers private driving licenses and motorcycle licenses only, and the remaining validity of the license must be less than 365 days. This guide explains the requirements as shown on the official service page at the time of writing, the renewal and delivery steps, why a request may not proceed, and how it differs from renewing the vehicle registration (Istimara).
What Is the Driving License Renewal Service on Absher and Who Can Use It?
The driving license renewal page on the National Portal describes a service that lets individuals renew their driving license electronically, easily and efficiently, without visiting traffic offices. It lists the service duration as immediate and the delivery channels as the website portal and smartphone apps. The Absher service guide defines the beneficiary as a citizen or resident who is registered and activated on the Absher platform.
So first make sure your Absher account is active and that you can log in, then check your license type. According to the prerequisites tab, the service covers renewing private driving licenses and motorcycle licenses only. If your license is of another type, do not assume this service will accept it; ask the official traffic channels about the right procedure for your case.
What Are the Published Driving License Renewal Requirements?
The official service page lists the following requirements. Use the table as a checklist before logging in to Absher, while following what the service displays for your case when you apply. Requirements may be updated, and the service page at the time you apply is the reference.
| Requirement as Shown on the Service Page | What to Check Before Starting |
| A private or motorcycle driving license | The license type recorded in your details |
| Payment of license renewal fees through government payments via banks | That payment was actually made for the correct service, not just that a payment screen was opened |
| Payment of traffic violations, if any | The status of any violations recorded against you before applying |
| Remaining license validity of less than 365 days | Your expiry date, using the driving license information service |
| A medical examination through a certified medical center | That the examination was done at a certified center |
The required documents tab repeats payment of any violations, payment of the renewal fees and the medical examination, and does not mention uploading photos or extra papers. Do not rely on circulated lists that add unpublished documents. If you have violations, review how to check and pay traffic violations before starting the renewal.
What Are the Steps for Driving License Renewal on Absher?
The following steps are taken from the service page on the National Portal. If the menus look different in your interface, look for the driving license renewal service under traffic services, and do not choose a similarly named service such as vehicle registration renewal.
- Log in to the Absher platform.
- Select “My Services”.
- Choose “Traffic” from the services list.
- Select the “Renew Driving License” service.
- Read the service description, terms and conditions, then select “Next”.
- Review your personal information, specify the renewal period (2 years, 5 years or 10 years), then select “Confirm Renewal”.
- Fill in your National Address details for license delivery.
- Review the entered data.
- Pay the delivery fees using a card (Visa, Mada, Mastercard).
- A message confirms that the driving license renewal is completed.
Note that the payment inside these steps is for delivery. For the renewal fees themselves, the prerequisites tab says they are paid through government payments via banks. This guide does not state amounts for any period; follow what the service shows for your case. Before filling in the address, make sure your National Address is correct, because it is used for the license delivery request.
Closing the screen or completing a payment alone does not prove the renewal is complete. Check for the success message, then review your license details before repeating any step if your session was interrupted.
Why Can License Renewal Fail to Proceed, and What Should You Check?
The service page does not publish a list of error messages, but the published requirements help you identify which item to review. Always start with the text of the message shown in your account, then compare it with the following possibilities:
- The remaining validity of the license is not less than 365 days; check the expiry date through the driving license information service.
- The renewal fees have not been paid or the payment has not appeared yet; review the transaction status and receipt before paying again.
- There are unpaid traffic violations; do not assume that filing a dispute replaces this requirement before its outcome is clear.
- There is no medical examination from a certified medical center.
- The license type is not covered, because the service is limited to private and motorcycle licenses.
- The account is not registered or activated on Absher, since the service guide defines the beneficiary as a registered and activated user.
If the message is unclear, note its text, the time of the attempt and the stage where you stopped, then contact the official support channels shown on the service page. Never share your password or verification code with anyone, and do not treat a failed attempt as a final rejection without confirmation from the competent authority.
How Does Driving License Renewal Differ From Istimara Renewal?
The two documents are often confused because both are called a license. The driving license belongs to the driver, while the Istimara is the vehicle registration and relates to the car itself. Each therefore has its own Absher service and its own requirements, so do not apply the conditions of one to the other.
The medical examination and the remaining license validity are published requirements for driving license renewal and have nothing to do with the condition of your car. If what you need to renew is the vehicle document, follow the guide to vehicle registration renewal on Absher and why it may fail, which explains that service’s requirements and steps.
Likewise, vehicle insurance does not appear among the driving license renewal requirements on the service page. If you are reviewing your car insurance at the same time for other reasons, read about comprehensive versus third-party car insurance to choose a suitable policy.
Frequently Asked Questions About Driving License Renewal
Can I renew my driving license without visiting a traffic office?
Yes, according to the official service page: the service is electronic through Absher without the need to visit traffic offices, provided the regulatory requirements are completed. If your case cannot proceed, follow the service message and the competent authority’s guidance.
How early can I renew my license before it expires?
The prerequisites tab requires the remaining validity of the license to be less than 365 days. You can check your license validity electronically through the driving license information service listed among the related services.
Is a medical examination required for driving license renewal?
Yes. The official page lists a medical examination through a certified medical center among both the prerequisites and the required documents. Complete the examination at a certified center before starting the service.
What renewal periods are available?
The service steps mention choosing the renewal period of 2 years, 5 years or 10 years while reviewing your details. Choose from the options shown to you and review what applies to each option as displayed in the service.
How do I receive my license after renewal?
The steps include filling in your National Address details for license delivery and then paying the delivery fees by card. The National Portal also lists a digital driving license display service among the related services, which is separate from renewal.
Conclusion
Prepare the driving license renewal requirements first: pay the fees and any violations, complete the medical examination at a certified center, and confirm that the remaining validity meets the published condition. Then follow the steps on Absher and check for the success message. If the request cannot proceed, address the item identified in the message or request clarification through the official channels.
Accident Damage Assessment in Saudi Arabia: Taqdeer Guide
Table of Contents:
|
Accident damage assessment is a step you may need after a Najm or traffic police report. According to the Saudi Authority for Accredited Valuers (TAQEEM), it means determining the cost of repairing the vehicle, including parts, or estimating its market value before or after the damage. These assessments are managed electronically through the Taqdeer system, which operates under the Authority’s supervision and lets you book an appointment and check the status of your assessment. This guide covers the stage after the report: when to seek an assessment, what to prepare, how to read the report and review it with your workshop and insurer, and what to do if you disagree with the result.
What Is Accident Damage Assessment and Who Oversees It?
On its official English website, TAQEEM describes vehicle damage assessment valuation as “the act or process of determining the value of repairing the vehicle including the spare parts, or estimating the market value of the vehicle before and after the accident”; the Arabic version also mentions labour explicitly. The outcome may therefore be a repair cost, or a market value before or after the damage, depending on the case.
TAQEEM describes Taqdeer as “an online integrated system for managing, operating, and organizing vehicle damage assessment processes” and lists “Book an appointment at Taqdeer centers” among its services. The Taqdeer system website (in Arabic) states that it operates under the supervision of the Saudi Authority for Accredited Valuers. An assessment is a technical valuation of the damage; it is neither the accident report nor your insurer’s decision.
When Do You Need an Assessment After a Najm or Police Report?
The sequence starts with attending to and documenting the accident. If you have not completed that stage, begin with the guide to Najm reporting steps and when to call the traffic police, then return to this guide.
The official pages we relied on do not state that an assessment is required for every accident, nor do they describe the content of report messages. Follow what the accident report and your insurer require in your case, and ask before any repair starts, because repairing damage before it is assessed may cost you the chance to document it as it was. Useful questions for your insurer:
- Does my case need a damage assessment, and from which body?
- Is the electronic report enough, or must it be sent in a particular way?
- Should I wait for the assessment before taking the car to a workshop?
- Which documents do you need with the report to progress the claim?
How Do You Book a Taqdeer Appointment and Track It?
The Taqdeer website presents the service in three consecutive stages, which can be summarised as follows:
- Book an appointment and go to the assessment center, using the booking service, which the site describes as booking a new appointment to assess your vehicle’s damage.
- Have the vehicle damage assessed at the assessment center.
- Receive the report electronically, with the option to follow it through the report status service, which lets you check the status of your assessment.
If your plans change before the appointment, the manage bookings service allows you, according to the site, to modify or cancel the booking, and the assessment centers page helps you find the nearest centers in your city. We do not mention numbers of centers, timings or fees here; follow what the service shows for your case when you book.
What Should You Prepare Before Visiting an Assessment Center?
The pages we reviewed do not publish a document list, so the list below is practical rather than an official requirement; what the booking screen and center ask for takes precedence:
- Your booking details as shown once the booking is complete.
- The accident report reference from Najm or the traffic police.
- Your ID and the vehicle registration; ask what is needed if you are not the vehicle owner.
- Unedited photos of the damage taken at the time of the accident.
- Your insurance policy details and the party handling the claim.
Do not repair the damage being assessed before the appointment unless the relevant authority tells you to, and do not drive an unsafe car; arrange transport if you notice a leak, a red warning light or a steering fault.
How Do You Read a Damage Assessment Report?
The report format may vary from case to case, but the Authority’s definition shows what it centres on: labour, spare parts, or market value before or after the damage. Use the table to review it item by item:
| Item | What to Check | What to Ask |
| Vehicle and accident details | The car and the accident reference match | Do these details relate to my car and this accident? |
| Spare parts | The listed parts compared with the documented damage | What type of part does the assessment assume? |
| Labour | Listed work such as bodywork and paint | Does the work cover all the damage I documented? |
| Market value | Whether a value before or after the damage is stated | On what basis was this value reached? |
To understand how the type of part affects a repair, see genuine vs aftermarket vs used car parts. Do not assume the report specifies the type of part unless it says so explicitly; ask about it.
How Do You Review the Assessment With Your Workshop and Insurer?
The assessment sets a value, while the compensation and repair path is governed by your policy and your insurer. Check your policy type and what it covers in the guide to comprehensive versus third-party car insurance, and do not assume that the assessed amount is what you will receive in every case.
- Show the report to the workshop before work starts and ask them to compare its items with what they will actually do.
- If hidden damage appears after disassembly, ask your insurer how it will be handled before the repair continues.
- Ask the workshop for an itemised invoice and photos before and after the repair.
- Record every contact with your insurer: the date, the person and what you were asked for.
If the car needs sensor or camera calibration after the repair, ask whether it is included in the assessment or in the workshop’s quote.
What Should You Do If You Disagree With the Assessment?
We did not find a published objection mechanism for assessment results on the official pages we reviewed, so we do not describe a specific procedure. The right step is to ask the source about the official procedure:
- Identify exactly which item you disagree with: a part, a piece of work or a market value.
- Gather supporting evidence: accident photos, the workshop’s notes after disassembly and any invoice.
- Contact Taqdeer through the support and help channels shown on its website and ask what procedure is available for your case.
- Also ask your insurer about its review procedure and what it needs from you in writing.
Do not accept a settlement you disagree with before you understand its consequences, and ask for written replies where possible.
Why Should You Keep the Assessment Report After the Repair?
The report and invoice help you later when you sell the car or when a buyer asks about the accident. The guide to reading a Mojaz report and its limits explains how accident records in a vehicle history should be understood and what cannot be concluded from them.
If you are a buyer looking at a car with signs of repair, ask for the assessment report and invoice if they exist, and use the guide on how to tell whether a car has been repaired alongside an independent technical inspection.
Frequently Asked Questions About Accident Damage Assessment
Is an accident damage assessment the same as a Najm report?
No. The report documents the accident, while the assessment estimates the repair cost or the market value of the vehicle before or after the damage.
Do I need an assessment for every accident?
Do not rely on a general rule; follow what the accident report and your insurer require in your case, and ask them before repairing the car.
How can I check the status of my assessment report?
The Taqdeer website offers an assessment status inquiry service and lists receiving the report electronically as one of the service stages.
Can I change or cancel my assessment appointment?
The website offers a manage bookings service for changes and cancellations; follow what the service shows for your booking.
Is the assessed amount the final compensation?
Not necessarily. Compensation depends on your policy and your insurer’s procedures, so ask your insurer how it is calculated in your case.
Conclusion
After the report, ask your insurer what your case needs, book the assessment through the official system and read the report item by item before any repair. If you disagree, ask Taqdeer and your insurer about the official procedure, and keep your documents for the future.
Choosing a Car Battery: Size, Capacity, Type and Installation
Table of Contents:
|
Choosing a car battery starts with confirming that the battery really is the cause of the problem, then matching what the owner’s manual or the current battery label specifies: size and mounting, terminal orientation, capacity in Ah, cold cranking amps (CCA) and battery technology. After that, check the manufacture date and warranty terms, and make sure installation is done properly, which may include registering the battery in the car’s system. This guide explains each step in general terms; your owner’s manual and a qualified technician remain the reference for your car’s specifications.
When Should You Start Choosing a Car Battery?
Do not buy a battery just because the car failed to start once. Weak starting can be linked to the battery, but also to the starter motor, the connections or the charging system. Ask a specialist to test the battery and charging system with suitable equipment, and review the car battery failure symptoms and how to test them to recognise signs worth checking.
If the engine cranks normally but does not start, the battery may not be the cause; see the guide on an engine that cranks but will not start. If the battery keeps going flat, there may be a hidden electrical drain in the car, and fitting a new battery without fixing the cause may simply pass the problem on to it. Once testing confirms the battery, prepare the following before visiting the seller:
- A clear photo of the current battery label showing all printed details.
- The battery specification page in the owner’s manual, if available.
- Whether the car has an automatic engine stop-start system.
- Where the battery sits: engine bay, boot or under a seat.
Which Specifications Should Match the Manual or Label?
The first reference is the owner’s manual, then the label of the original battery if it is still fitted. The table below summarises what to compare before paying and where to find it.
| Item | Where to find it | Why it matters |
| Size or group | Owner’s manual or current battery label | Defines overall dimensions and fit on the tray |
| Mounting dimensions | Battery tray and hold-down clamp | A poorly secured battery vibrates and can be damaged |
| Terminal orientation | Position of the positive and negative terminals on the current battery | A different layout may stop cables reaching or strain them |
| Capacity (Ah) | Label or owner’s manual | Indicates the energy stored in the battery |
| Cold cranking amps (CCA) | Label | Indicates the battery’s ability to deliver starting current |
| Technology type | Label and owner’s manual | Must suit the charging system and any stop-start system |
Two batteries can look alike yet differ in terminal orientation, height or mounting lip. Ask the seller to compare the new battery directly with the old one. If the current label differs from the manual, the previous battery may not have matched in the first place; rely on the manual or ask the dealer or a qualified technician.
What Do Capacity (Ah) and Cold Cranking Amps (CCA) Mean?
Capacity in Ah describes how much energy the battery stores, which matters when the battery powers the car’s systems with the engine off. Cold cranking amps (CCA) describe the battery’s ability to deliver a high current at the moment of starting in cold conditions, according to a specific test standard.
A label may state CCA according to a different standard from another battery, so only compare two figures measured to the same standard, and ask the seller to clarify. The general rule is not to go below the car’s specified capacity or current.
On the other hand, a higher figure is not automatically better; what matters is that the battery keeps the correct size and technology. In cars that record battery data in their system, the actual capacity of the new battery may need to be entered during registration, so tell the technician about any difference from the original.
What Is the Difference Between Flooded, EFB and AGM Batteries?
The general idea of each type is as follows, while the manual decides what your car needs:
- Conventional flooded battery: common in cars without an automatic stop-start system; some serviceable types need the electrolyte level checked.
- EFB battery: an enhanced flooded battery built to withstand repeated starting and discharge cycles better than a conventional one, used in many cars with stop-start systems.
- AGM battery: the electrolyte is absorbed in glass fibre mats and the battery is sealed; it copes better with electrical loads and repeated discharge, and is used in cars with higher electrical demands.
In a car with automatic stop-start, the battery handles frequent engine restarts and powers systems while the engine is stopped. Fitting a lower technology than specified, such as a conventional flooded battery instead of EFB or EFB instead of AGM, may weaken system performance, shorten battery life and trigger warning messages. Moving to a higher technology should only happen if the owner’s manual or the dealer allows it.
If the battery sits inside the cabin or boot, the manufacturer may specify a sealed type or a particular vent outlet; do not fit a different battery in that location without confirming that it matches.
How Do You Read the Manufacture Date and Warranty Terms?
The manufacture date usually appears as a code printed on the lid or case or on a small sticker, and the code format differs between manufacturers, so ask the seller to explain the code on the battery itself, and prefer the most recently made battery among the matching options.
A battery stored for a long time may lose some charge, so ask whether the seller tested it before sale. For the warranty, read the written terms on the invoice or warranty card rather than relying on a verbal promise, and pay attention to the following:
- What the warranty covers, how a fault is proven, and whether the battery must be tested by the seller.
- Whether installation elsewhere, or fitting the battery to a car it does not match, affects the warranty.
- Which documents are needed for a claim; keep the invoice somewhere easy to find.
How Does Saudi Heat Affect Your Battery Choice?
High temperatures speed up the reactions inside a battery and may increase fluid loss and ageing of the internal plates. This does not mean choosing a battery simply because it is marketed for heat; it means sticking to the correct specification and technology and choosing a recently made battery.
After installation, help the battery by parking in the shade where possible, keeping the terminals clean and checking the battery and charging system during routine maintenance. For more on how heat affects the car in general, read the summer car care guide for Saudi heat.
What Should You Consider When Installing the New Battery?
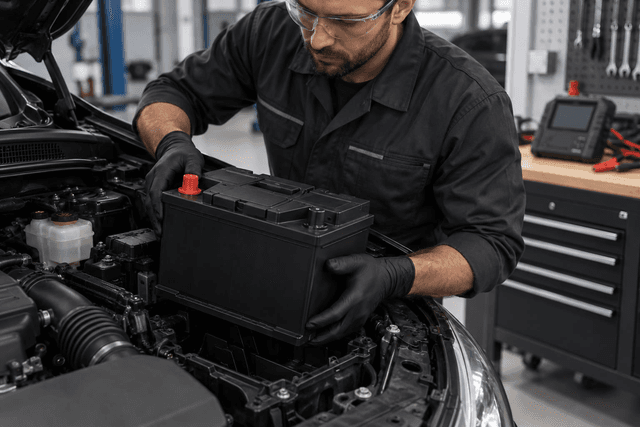
If you are not confident about the steps, leave the installation to a qualified technician. If you fit it yourself, wear eye protection and gloves, switch the engine off and keep the key away, disconnect and reconnect the terminals in the order given in the owner’s manual, avoid letting a metal tool touch both terminals, and keep any sparks or flames away from the battery.
- Battery registration: some cars require the new battery to be registered in the energy management system with a diagnostic tool so that charging is adjusted for a new battery. Ask the technician whether your car needs this.
- Saving settings: disconnecting the battery may erase settings such as the clock and radio, and some systems may need resetting according to the manual. Some technicians use a memory saver during the swap.
- Clean terminals: remove corrosion from the terminals and cable ends, and check that the clamps are sound before connecting.
- Secure mounting: fix the battery with its hold-down clamp so it cannot move, tighten the terminals without excessive force, and refit the protective covers.
After installation, start the car and watch for any warning message. If one appears, return to the technician to check the installation and registration rather than trying to clear the warning yourself.
How Do You Dispose of the Old Battery Safely?
A battery contains acid and lead, so do not open it, drain it or put it in household waste. Keep it upright, protect its terminals from contact, and hand it to the seller, a workshop or a party that accepts used batteries for recycling. If it is cracked or leaking, do not touch it with bare hands and ask the workshop to handle it.
Frequently Asked Questions About Choosing a Car Battery
How can I tell a battery fault from a starter fault?
Slow cranking with dim lights may point to the battery, while a click with bright lights may point to the starter motor. These are indications, not a diagnosis, so have the battery and charging system tested and review the signs of a failing starter motor before buying.
Can I fit a battery with a higher capacity than the original?
It may be possible in some cases if the size and technology still match, but the decision rests with the owner’s manual and the technician, especially in cars that record battery data in their system.
Can I fit a conventional battery to a car with stop-start?
This is not recommended; use the technology specified in the manual, such as EFB or AGM, because a lower technology may not withstand the frequent restart pattern.
Do all cars need the new battery to be registered?
No, but some cars require it using a diagnostic tool. Ask the technician or check the manual before installation, and do not assume the swap is complete once the terminals are connected.
What should I do with the old battery after replacing it?
Do not open it or throw it away with household waste. Keep it upright and hand it to the seller, a workshop or a party that accepts used batteries for recycling.
Conclusion
First confirm that the battery is the problem, then match size, terminals, capacity, CCA and technology to the owner’s manual, and check the manufacture date and warranty terms. Leave installation and registration to a technician if you are unsure, and dispose of the old battery safely.
Instalments at the Cash Price: Meaning and What to Check
Table of Contents:
|
An offer of instalments at the cash price basically means that the total you pay for the car in instalments equals its price if you paid the full amount at once, so the finance cost is not added to the car’s price because the seller or the offer absorbs it. But the advertising phrase instalments at the cash price is not enough on its own; there may still be administration fees, comprehensive insurance required throughout the contract, a final payment, or add-ons bundled into the offer. So ask for the cash price and the total amount payable in writing, compare the two, and read the repayment schedule, the offer’s terms and its validity before you sign.
What Do Instalments at the Cash Price Mean?
The idea is that you buy the car in instalments without its price rising above the cash price. In ordinary financing, the buyer pays the finance cost on top of the car’s price, which is what the finance company charges for spreading the amount over the contract term. In this type of offer, it is announced that this cost does not fall on the buyer, so the down payment, the instalments and any other payments together remain equal to the cash price.
Searches use several similar phrases, such as cash price instalment cars, a car on instalments at the cash price and two payments at the cash price, and the general meaning is the same: the contract price equals the full-payment price. For the general comparison between cash and instalments, with the pros and cons of each option and how to calculate the total cost, see the comparison of buying a car with financing or cash, while this article focuses specifically on instalments at the cash price and how to verify them.
How Do Cash Price Instalment Offers Usually Work?
The details of each offer differ, but the general picture is often similar: the seller agrees with a finance company to absorb all or part of the finance cost, so it appears to the buyer that what they pay does not exceed the cash price. The financing itself is provided by the finance company according to its terms and is subject to its credit approval, so the existence of an offer does not mean your application is automatically accepted.
- The offer may be limited to specific cars or trims, or to a certain quantity.
- It may be tied to a specific instalment term or a specific down payment, so if you change the term or the down payment the calculation changes and your application may fall outside the offer.
- It may be for a limited time, so it can expire or its terms can change while an old advertisement stays the same.
- It may not combine with discounts given to cash buyers, so the cash price stated in the offer may be higher than what you could get by paying the full amount.
In some cases the offer is at the cash price in name only, because the cost moves to other items such as fees or add-ons. That is why what counts is the total amount written in the contract, not the headline of the advertisement. At Saleh Cars Group, financing solutions are offered through approved banks and finance companies, and the financing is provided by the finance company, not the group; you can review the frequently asked questions about buying and financing to learn about payment methods and general financing conditions.
What Other Costs May Remain Even If the Offer Is at the Cash Price?
Even if no finance cost is added to the car’s price, other items may still apply, varying by offer and by the finance company’s terms. The table summarises the main ones and what to ask before signing:
| Item | What it may mean | What to ask |
| Administration or application processing fees | An amount the finance company charges for reviewing the application or opening the contract | Are there fees? Are they inside or outside the total amount? |
| Comprehensive insurance during the contract | The finance company may require comprehensive insurance on the car throughout the instalment term | Is the insurance at my expense? Who chooses the insurer? How is it renewed? |
| Down payment | Part of the price paid when the contract is signed | Does the offer require a specific down payment? Does the offer still apply if I change it? |
| Final payment | An amount larger than the monthly instalment due at the end of the contract | Is there a final payment in the repayment schedule? What are my options when it is due? |
| Add-ons bundled into the offer | Service packages, accessories, window tinting or protection added to the price | Are the add-ons mandatory? Can they be removed while keeping the offer? |
| Early settlement | The terms for ending the contract before its due date | Are there fees or conditions for early settlement? How are they calculated? |
The contract may also include items other than these. Ask for every item in writing, and check the contract and the finance company’s official disclosures, because these details differ from one contract to another; anything you do not understand, ask the finance company directly.
How Can You Verify That an Offer Is Really at the Cash Price?
- Ask for the cash price of exactly the same car, with the same trim, specifications and colour, in writing in an official quotation.
- Ask for the total amount payable under the instalment plan in writing: the down payment, the sum of the instalments, any final payment and all fees.
- Compare the two figures: if the total amount is higher than the cash price, the difference is what you are actually paying for the instalments, whatever the offer is called.
- Ask for the full repayment schedule, and make sure the number of instalments, their amounts and their due dates match what you were told verbally.
- Read the offer’s terms: the cars included, the permitted instalment term, the required down payment and the offer’s expiry date.
- Before signing, make sure the finance company’s offer and the contract state the same figures as the seller’s quotation.
To get a first estimate of the monthly instalment before visiting the showroom, you can use the car instalments and finance calculator page, bearing in mind that the final figures are set by the finance company according to its terms, and that a first estimate does not replace the official repayment schedule.
What Questions Should You Ask Before Signing?
- Is the cash price in the offer the same price I would pay if I bought in cash today, or does the cash discount not apply to the offer?
- What total amount will I pay up to the last instalment, including all fees and add-ons?
- Who bears the finance cost, and does that change if I change the term or the down payment?
- Is comprehensive insurance required throughout the contract, and who pays for its renewal?
- Is there a final payment in the contract, and what are my options when it is due?
- What are the early settlement terms, and do the offer’s benefits remain if I settle early?
- When does the offer end, and what happens if it ends before the finance company decides on my application?
Write down the answers and ask for them in writing, and never sign a contract with blank fields or terms that were not explained to you. For the other buying steps, from setting a budget to inspecting and receiving the car, see the new car buying guide before you sign and take delivery.
When Does an Instalment Offer at the Cash Price Suit You?
The offer usually suits you when you have already decided on instalments, and the comparison shows that the total amount really equals the cash price, and the car included is the one you need rather than the one the offer pushes. Signs that make it a reasonable option include:
- The monthly instalment is comfortable for your income and does not strain your other commitments.
- The insurance terms, fees and add-ons are clear and acceptable to you.
- You prefer to keep part of your savings rather than paying the car’s full value.
It may not suit you if the car included does not fit your needs, if the down payment or final payment is larger than you can manage, or if an available cash discount makes paying in full better value for you. If what you have does not cover a down payment at all, that is a different question about buying without a down payment, with its own conditions at finance companies. Before you decide, you can browse the current offers on cars and check the terms and validity of each offer.
Frequently Asked Questions About Instalments at the Cash Price
Does instalments at the cash price mean there is no extra cost at all?
Not necessarily. The seller may absorb the finance cost, but administration fees, comprehensive insurance or bundled add-ons may still apply. What counts is the total amount in writing compared with the cash price of the same car.
What does two payments at the cash price mean?
It usually means splitting the car’s price into two payments with no increase over the cash price, according to the seller’s terms. Ask when each payment is due and when the car is delivered and ownership transferred, and get this in writing.
Do cash price instalment offers cover all cars?
Usually not; the offer may be limited to specific cars, trims or quantities and for a limited time. Read the offer’s terms and expiry date before relying on it in your decision.
Is early settlement possible with these offers?
That depends on the finance company’s terms and the contract. Ask the finance company about the early settlement conditions and any fees, and about the effect on the offer’s benefits, and get the answer in writing.
Can a resident buy a car on instalments at the cash price?
Residents can buy with financing, but acceptance of the application and the required documents are set by the finance company according to its terms and credit approval, and each offer’s conditions may differ, so ask the finance company before applying.
Conclusion
Instalments at the cash price mean that the contract price equals the full-payment price, but they do not always mean the absence of any other cost. Ask for the cash price and the total amount in writing and compare them, review the repayment schedule, fees, insurance, final payment, early settlement terms and the offer’s validity, and sign only if the figures are clear and suit your budget.